एनएफ़टी लोन क्या है?
नाम से ही साफ़ है: एनएफ़टी लोन क्रिप्टो जगत में कर्ज़ का एक ऐसा रूप है, जिसमें अपूरणीय टोकन (NFT) को गिरवी रखा जाता है। पहले विकेंद्रीकृत वित्त (DeFi) में कर्ज़ के लिए बिटकॉइन और ईथर जैसे परस्पर विनिमेय टोकन इस्तेमाल होते थे। लेकिन एनएफ़टी की बढ़ती कीमत और लोकप्रियता के साथ, अब मंच एनएफ़टी धारकों को अपनी संपत्ति गिरवी रखकर कर्ज़ लेने का विकल्प दे रहे हैं।
एनएफ़टी के कई नामी संग्रहों में कुछ एकल टोकन की कीमत दसियों हज़ार डॉलर तक पहुँचती है। एनएफ़टी लोन की मदद से उनके मालिक एनएफ़टी बेचे बिना आसानी से नकदी जुटा सकते हैं। इससे विकेंद्रीकृत वित्त का दायरा डिजिटल कला, संग्रहणीय वस्तुओं, आभासी अचल संपत्ति और टोकन के रूप में मौजूद दूसरी अनूठी संपत्तियों तक फैलता है।
एनएफ़टी लोन के फायदे
एनएफ़टी लोन के कई फायदे हैं, जिनमें शामिल हैं:
- Liberation of liquidity
महँगे एनएफ़टी रखने वाले लोग अपनी संपत्ति बेचे बिना नकदी जुटा सकते हैं। यह उन लोगों के लिए खास तौर पर उपयोगी हो सकता है जिन्हें अपने एनएफ़टी की दीर्घकालीन कीमत पर भरोसा है, लेकिन जिन्हें तुरंत पैसों की ज़रूरत है।
- Enlarging the domain of DeFi into the realm of digital art
एनएफ़टी लोन, एनएफ़टी मालिकों को कर्ज़ के ज़रिये DeFi में शामिल होने का रास्ता देते हैं। यह सुविधा एनएफ़टी जगत के कलाकारों और उत्साही लोगों के लिए खास मायने रख सकती है, क्योंकि वे अपनी डिजिटल संपत्तियों का इस्तेमाल DeFi में कर सकते हैं।
- Exemption from credit assessments
DeFi के दूसरे कर्ज़ों की तरह, एनएफ़टी को गिरवी रखकर मिलने वाले कर्ज़ के लिए क्रेडिट जाँच की ज़रूरत नहीं पड़ती। इससे कम क्रेडिट स्कोर वाले या पारंपरिक बैंकिंग सेवाओं तक सीमित पहुँच रखने वाले लोगों को फायदा हो सकता है।
एनएफ़टी लोन के संभावित जोखिम
ध्यान रहे कि एनएफ़टी लोन में कुछ जोखिम जुड़े हैं, जिन पर गंभीरता से विचार करना चाहिए। एनएफ़टी की कीमत में भारी उतार-चढ़ाव हो सकता है, इसलिए उसका सही मूल्य तय करना मुश्किल पड़ सकता है। इसके अलावा, आम क्रिप्टोकरेंसी की तुलना में एनएफ़टी को आसानी से नकदी में बदलना कठिन होता है। ऐसे में, अगर कर्ज़ लेने वाला अपनी देनदारी पूरी नहीं कर पाता, तो कर्ज़दाता को एनएफ़टी बेचकर अपनी लगाई रकम वसूलने में परेशानी हो सकती है।
एनएफ़टी लोन से जुड़े जोखिमों में ये बातें शामिल हैं:
- Price Volatility: The value of NFTs often experiences marked fluctuations, rendering the accurate evaluation of their value for loan collateral purposes a formidable task. This situation could potentially result in scenarios where the assessed value of NFT plummets below the designated loan value, ultimately triggering a process of liquidation.
- Lack of Liquidity: NFTs commonly exhibit diminished liquidity compared to their crypto counterparts. In cases where a borrower defaults on their loan, the lender could find themselves grappling with challenges while attempting to offload the NFT in order to reclaim their invested capital.
- Smart Contract Risk: NFT loans, akin to various other DeFi protocols, are typically governed by smart contracts. These digital agreements are susceptible to bugs or vulnerabilities that malicious actors might exploit, potentially leading to the loss of either funds or NFTs.
- Regulatory Uncertainty: Similar to other aspects of the DeFi landscape, there exists a level of ambiguity regarding the regulatory framework encompassing NFT loans. The evolution of future regulations holds the potential to impact the feasibility of NFT loans and potentially introduce supplementary compliance prerequisites.
एनएफ़टी लोन कैसे लें?
एनएफ़टी लोन, क्रिप्टो कर्ज़ की तरह ही काम करते हैं। इसकी आसान रूपरेखा कुछ इस तरह है:
- Loan Request by Users: Individuals who own NFTs use these digital assets as collateral and submit loan requests through lending platforms specifically designed to accommodate NFT loans.
- Assessment of NFT Value: The lending platform, or participants within the platform, evaluate the NFT’s worth. This evaluation can be more straightforward when the NFT boasts a consistent value history in secondary markets. However, for NFTs with limited historical data or uniqueness, valuation becomes complex due to the subjective nature of determining their value.
- Granting the Loan: After reaching a consensus on the NFT’s value, the lender disburses a loan to the NFT holder. This loan is typically issued in a stablecoin. A smart contract is then employed to secure the NFT within it until the loan is fully repaid. The smart contract defines the specifics of the loan, including the desired loan amount, duration, and applicable interest rate.
- Repayment of the Loan: Upon the borrower’s successful repayment of the loan, the NFT is released from the smart contract and returned to the owner. Conversely, if the borrower fails to fulfill the loan terms, the smart contract executes an automatic transfer of the NFT to the lender. This process is commonly referred to as “liquidation.”
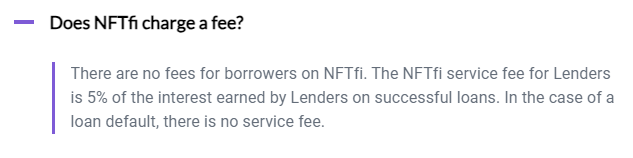
एनएफ़टी लोन देने वाले मंचों को उनकी सेवाओं की सूची देखकर या अलग-अलग DeFi (विकेंद्रीकृत वित्त) विकेंद्रीकृत ऐप (dApps) तलाशकर ढूँढ़ा जा सकता है। कर्ज़ लेने का अनुभव अच्छा रहे, इसके लिए अच्छी शर्तों, भरोसेमंद प्रतिष्ठा और पुराने काम के ठोस रिकॉर्ड वाला मंच चुनने से पहले अच्छी तरह पड़ताल करें। एनएफ़टी लोन देने वाले लोकप्रिय ऐपों में से एक NFTfi है। NFTfi सफल कर्ज़ों पर कर्ज़दाताओं को मिले ब्याज का ५% सेवा शुल्क लेता है, जबकि कर्ज़ लेने वालों से कोई शुल्क नहीं लिया जाता (NFTfi एक सीधे कर्ज़दाता और कर्ज़ लेने वाले के बीच काम करने वाला प्रोटोकॉल है; कर्ज़ की सभी शर्तें दोनों पक्ष तय करते हैं)।
NFTfi का मंच ३१ अगस्त २०२६ को बंद हो गया और अब वहाँ नए कर्ज़, प्रस्ताव, पुनर्वित्त या अवधि बढ़ाने की सुविधा उपलब्ध नहीं है। मौजूदा कर्ज़ों का भुगतान अब भी किया जा सकता है या ब्लॉकचेन पर ज़ब्ती की कार्रवाई हो सकती है।
निष्कर्ष
डिजिटल कला से लेकर अचल संपत्ति तक, कई तरह की संपत्तियों को टोकन में बदलने की सुविधा के चलते एनएफ़टी तेज़ी से लोकप्रिय हुए हैं। एनएफ़टी लोन का उभरना विकेंद्रीकृत वित्त (DeFi) की दुनिया में एक दिलचस्प नया कदम है, जो अनूठी डिजिटल संपत्तियों के मालिकों को नकदी जुटाने के नए रास्ते देता है।
एनएफ़टी लोन से मालिकों को अपनी संपत्ति में फँसी नकदी तक पहुँचने का नया तरीका ज़रूर मिलता है, लेकिन इसके साथ जुड़े बड़े जोखिमों को नज़रअंदाज़ नहीं करना चाहिए। एनएफ़टी लोन या किसी दूसरे DeFi प्रोटोकॉल का इस्तेमाल करने से पहले, इन जोखिमों को पूरी तरह समझना ज़रूरी है, ताकि सोच-समझकर फ़ैसला लिया जा सके।
स्रोत
- NFTfi — NFTfi बंद हो गया (३१ अगस्त २०२६)