NFT 대출이란?
NFT 대출은 말 그대로 대체 불가능 토큰(NFT)을 담보로 삼는 가상자산 대출입니다. 탈중앙화 금융(DeFi)에서는 그동안 비트코인이나 이더리움처럼 대체 가능한 토큰을 담보로 대출을 제공해 왔습니다. 하지만 NFT의 가치가 오르고 인기가 널리 퍼지면서, 이제는 NFT를 담보로 맡기고 대출을 받을 수 있는 플랫폼도 생겨나고 있습니다.
유명 NFT 컬렉션 가운데는 개별 작품의 가치가 수만 달러에 이르는 경우도 있습니다. NFT 대출을 이용하면 NFT를 팔지 않고도 유동성을 확보할 수 있습니다. 탈중앙화 금융의 영역을 디지털 아트와 수집품, 가상 부동산 등 다양한 토큰화 자산으로 넓혀 주는 방식입니다.
NFT 대출의 장점
NFT 대출에는 다음과 같은 여러 장점이 있습니다.
- Liberation of liquidity
가치가 높은 NFT를 보유한 사람은 자산을 처분하지 않고도 유동성을 확보할 수 있습니다. NFT의 장기적인 가치를 믿지만 당장 자금이 필요한 사람에게 특히 유용할 수 있습니다.
- Enlarging the domain of DeFi into the realm of digital art
NFT 대출은 NFT 보유자가 대출을 이용해 DeFi에 참여할 길을 열어 줍니다. 디지털 자산을 DeFi 생태계에서 활용할 수 있어 NFT 분야의 예술가나 애호가에게 특히 매력적인 선택지가 될 수 있습니다.
- Exemption from credit assessments
다른 DeFi 대출과 마찬가지로 NFT 담보 대출은 신용 심사가 필요하지 않습니다. 신용 점수가 낮거나 기존 은행 서비스를 이용하기 어려운 사람에게 큰 장점이 될 수 있습니다.
NFT 대출의 잠재적 위험
NFT 대출에는 간과해서는 안 될 위험이 따릅니다. NFT의 가치는 크게 요동칠 수 있어 정확한 가격을 매기기 어렵습니다. 또한 NFT는 일반적인 가상자산보다 유동성이 낮은 편입니다. 따라서 대출자가 상환 의무를 다하지 못할 경우, 대출자는 투자금을 회수하기 위해 NFT를 팔려 해도 매각에 어려움을 겪을 수 있습니다.
NFT 대출에는 다음과 같은 위험이 따릅니다.
- Price Volatility: The value of NFTs often experiences marked fluctuations, rendering the accurate evaluation of their value for loan collateral purposes a formidable task. This situation could potentially result in scenarios where the assessed value of NFT plummets below the designated loan value, ultimately triggering a process of liquidation.
- Lack of Liquidity: NFTs commonly exhibit diminished liquidity compared to their crypto counterparts. In cases where a borrower defaults on their loan, the lender could find themselves grappling with challenges while attempting to offload the NFT in order to reclaim their invested capital.
- Smart Contract Risk: NFT loans, akin to various other DeFi protocols, are typically governed by smart contracts. These digital agreements are susceptible to bugs or vulnerabilities that malicious actors might exploit, potentially leading to the loss of either funds or NFTs.
- Regulatory Uncertainty: Similar to other aspects of the DeFi landscape, there exists a level of ambiguity regarding the regulatory framework encompassing NFT loans. The evolution of future regulations holds the potential to impact the feasibility of NFT loans and potentially introduce supplementary compliance prerequisites.
NFT 대출은 어떻게 받을까?
NFT 대출은 가상자산 대출과 비슷한 방식으로 운영됩니다. 간단히 살펴보면 다음과 같습니다.
- Loan Request by Users: Individuals who own NFTs use these digital assets as collateral and submit loan requests through lending platforms specifically designed to accommodate NFT loans.
- Assessment of NFT Value: The lending platform, or participants within the platform, evaluate the NFT’s worth. This evaluation can be more straightforward when the NFT boasts a consistent value history in secondary markets. However, for NFTs with limited historical data or uniqueness, valuation becomes complex due to the subjective nature of determining their value.
- Granting the Loan: After reaching a consensus on the NFT’s value, the lender disburses a loan to the NFT holder. This loan is typically issued in a stablecoin. A smart contract is then employed to secure the NFT within it until the loan is fully repaid. The smart contract defines the specifics of the loan, including the desired loan amount, duration, and applicable interest rate.
- Repayment of the Loan: Upon the borrower’s successful repayment of the loan, the NFT is released from the smart contract and returned to the owner. Conversely, if the borrower fails to fulfill the loan terms, the smart contract executes an automatic transfer of the NFT to the lender. This process is commonly referred to as “liquidation.”
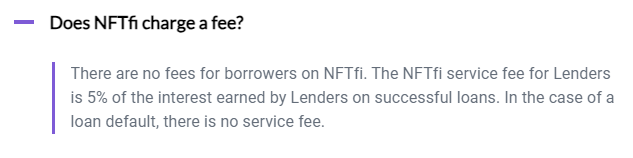
NFT 대출 플랫폼은 각 플랫폼의 상품 안내를 살펴보거나 여러 DeFi(탈중앙화 금융) 탈중앙화 애플리케이션(dApp)을 찾아보면 확인할 수 있습니다. 조건이 유리하고 평판이 탄탄하며 실적을 입증한 플랫폼을 고르려면 충분히 조사하는 것이 좋습니다. NFT 대출 dApp 가운데 가장 인기 있는 곳 중 하나는 NFTfi입니다. NFTfi는 대출이 성사되면 대여자가 얻는 이자의 5%를 대여자에게 서비스 수수료로 부과하며, 차입자 수수료는 0%입니다. NFTfi는 개인 간 거래 프로토콜로, 대출 조건은 대여자와 차입자가 직접 정합니다.
결론
NFT는 디지털 아트부터 부동산까지 다양한 자산을 토큰화할 수 있어 큰 인기를 얻었습니다. NFT 대출의 등장은 탈중앙화 금융(DeFi) 분야의 흥미로운 발전으로, 특별한 디지털 자산을 보유한 사람들에게 새로운 유동성 확보 수단을 제시합니다.
NFT 대출은 자산에 묶인 유동성을 활용할 수 있는 새로운 방법이지만, 그에 따르는 상당한 위험도 반드시 고려해야 합니다. NFT 대출이나 다른 DeFi 프로토콜을 이용하기 전에 위험을 충분히 이해하고 신중하게 판단해야 합니다.
출처
- NFTfi — NFTfi 서비스 종료 (2026년 8월 31일)